White-label family banking app Your family banking app, assembled for parents and kids.

A banking app for families: parents open accounts and cards for their children, pay a weekly allowance, set chores and savings goals and decide where each card works, while teens get an app of their own. Branded as yours and owned 100% by you.

  • 10proven modules
  • 100%yours, source included
A fuchsia piggy bank with a gold euro coin over its slot, beside a phone showing two children's balances and a fuchsia payment card

The product

From sign-up to every payment a child makes.

The screens your customers use, in the order they meet them, shown with demo data. Your logo, colours and domain go on top.

Mobile app for iOS and Android

  1. 01

    The family, set up in minutes

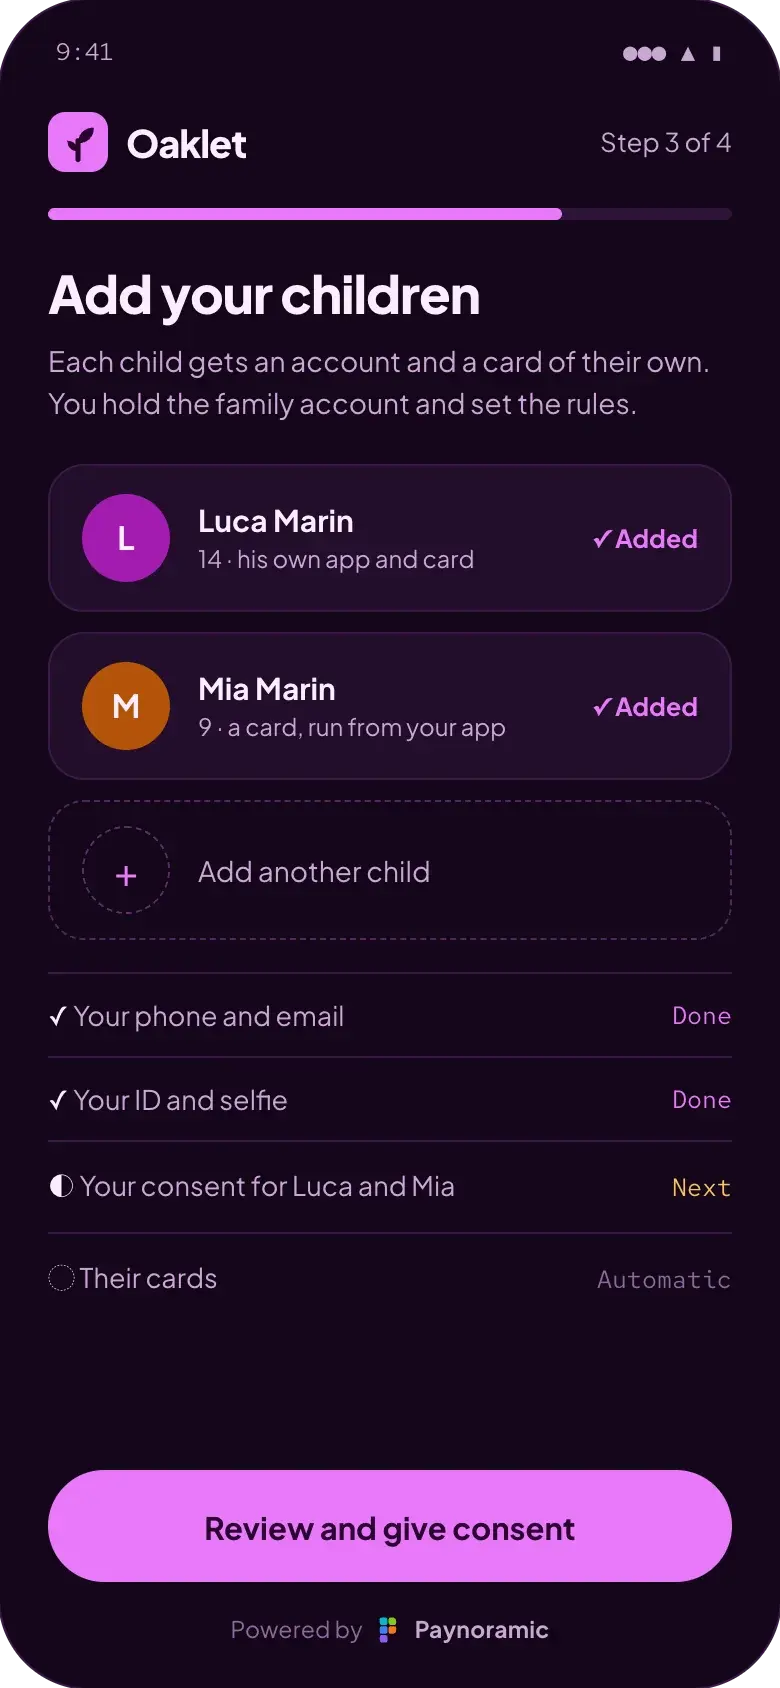
    A parent verifies once with an ID scan and a selfie, adds each child and gives consent for them in the app. Every child gets an account and a card, and teens get an app of their own.

    • The parent verified with ID and liveness checks
    • Consent recorded for every child
    • An account and a card for each child
    Oaklet family banking app onboarding, powered by Paynoramic: a parent adding Luca, 14, and Mia, 9, before giving consent
  2. 02

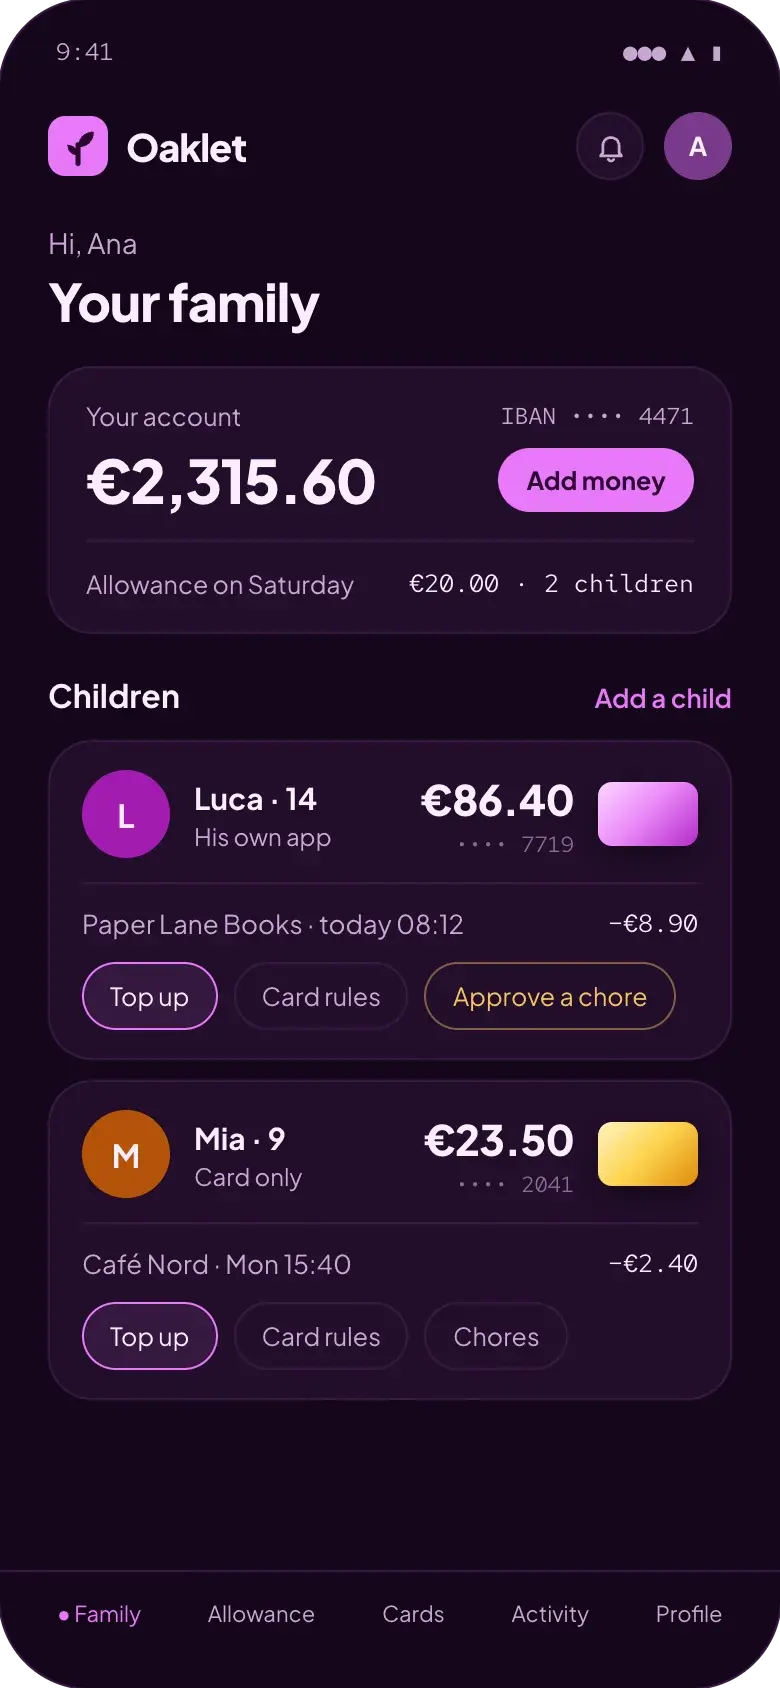
    Every child at a glance

    The parent's home shows each child's balance, card and latest payment next to their own account. Topping up a child takes one tap, and the money is there at once.

    • Each child's balance and card
    • Instant top-ups from the parent's account
    • Every payment as it happens
    Oaklet parent view: the family account, and Luca's and Mia's balances, cards and latest payments
  3. 03

    Allowance on time, chores on top

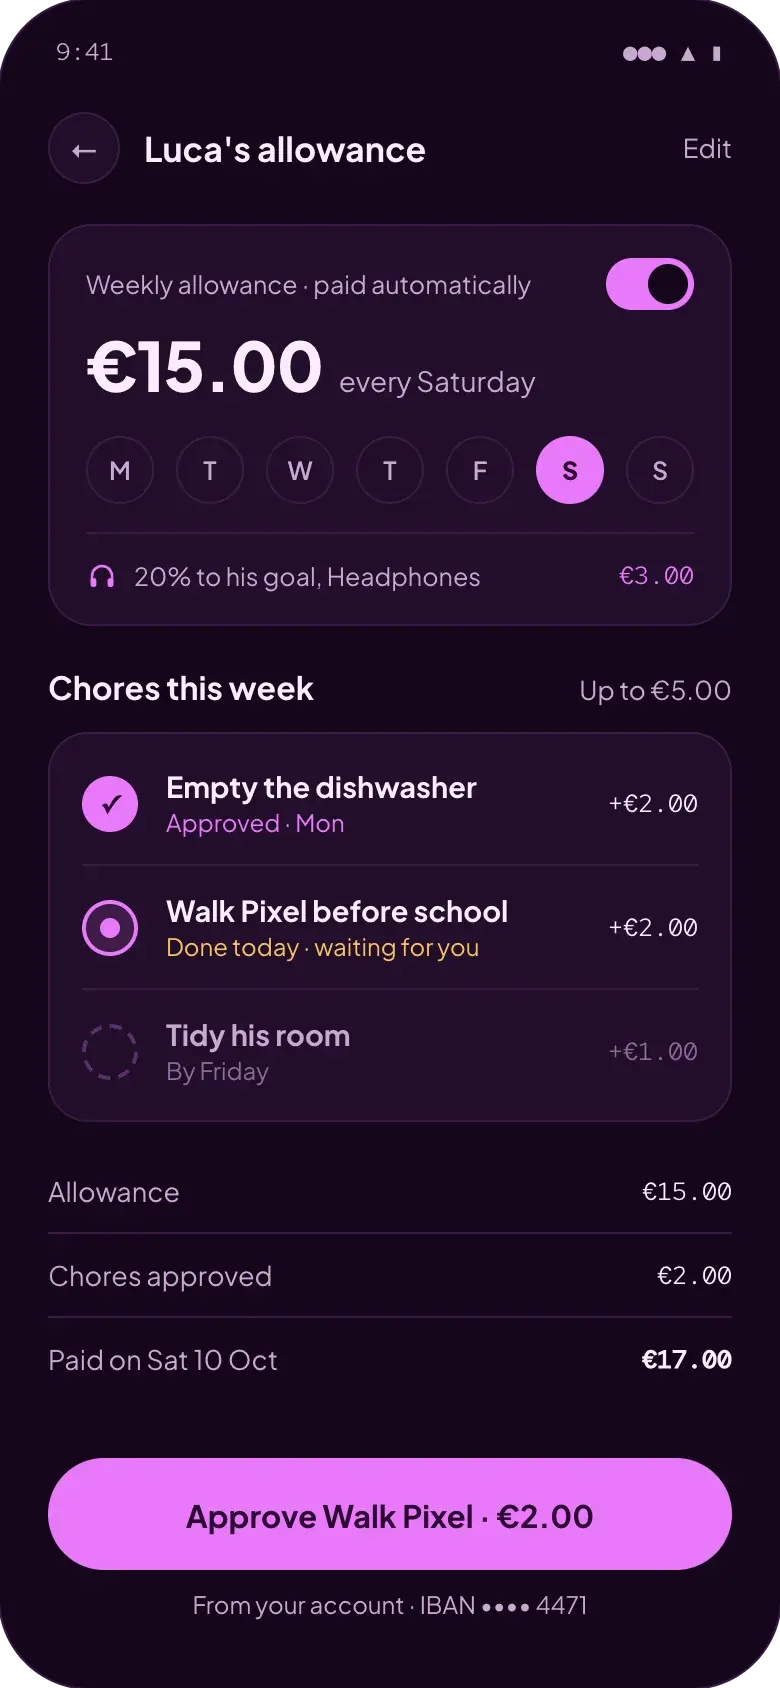
    Parents set a weekly or monthly allowance and the chores that add to it. A child ticks off a chore, the parent approves it, and it is all paid together on allowance day, with a share going straight to a savings goal.

    • Allowance paid automatically, weekly or monthly
    • Chores with a reward and a parent's approval
    • A share of every allowance saved for a goal
    Luca's weekly allowance of €15.00 every Saturday, with chores worth up to €5.00 and one waiting for approval
  4. 04

    Their own app, their own goals

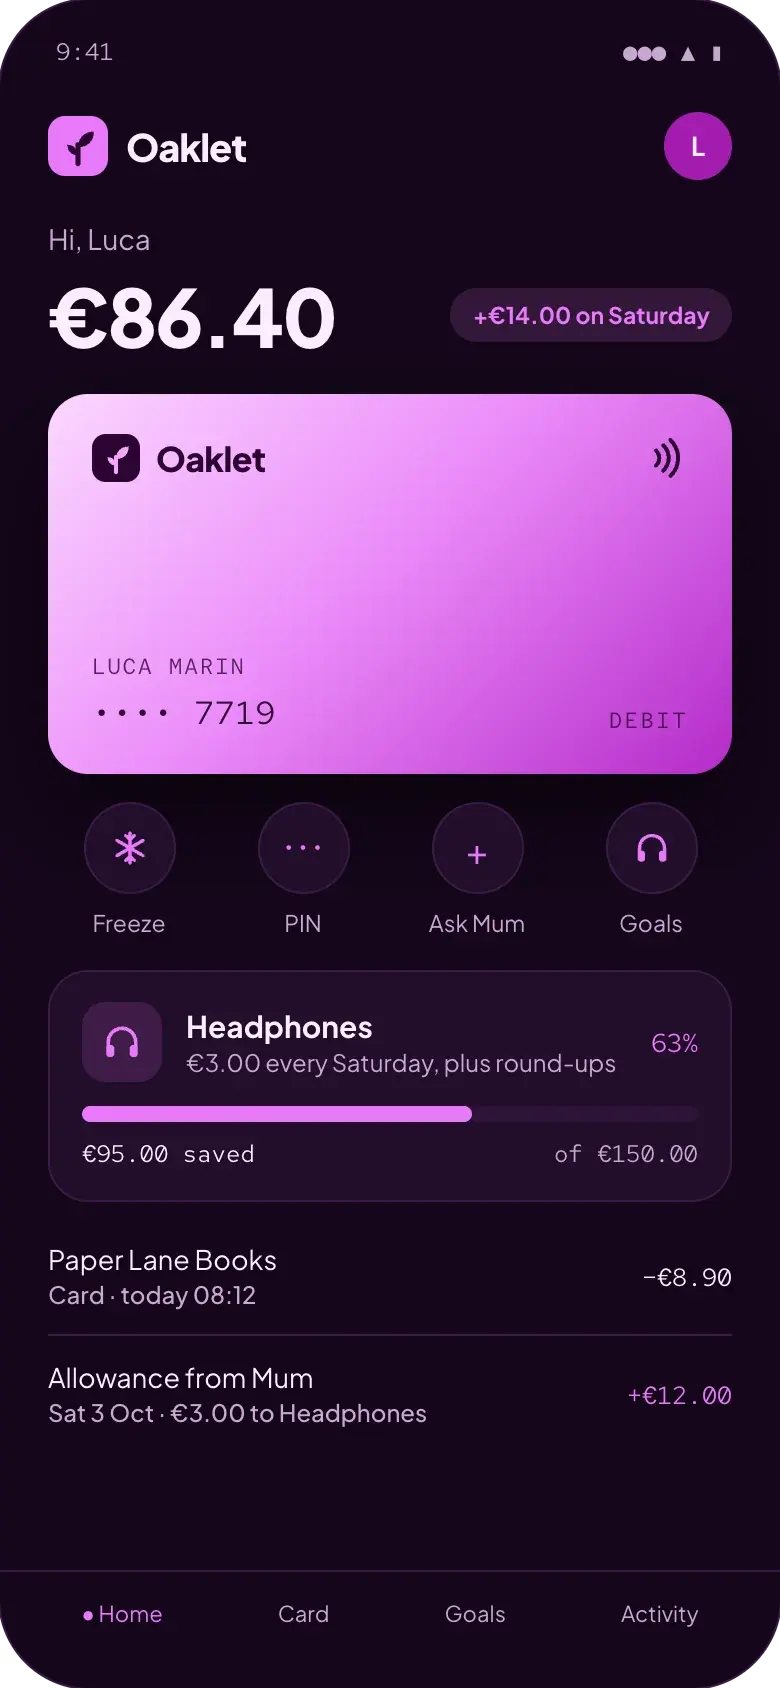
    Teens sign in to an app of their own: their balance, their card and the goals they save for, with round-ups from every payment. They can freeze the card or ask a parent for money themselves.

    • The teen's own sign-in, balance and card
    • Savings goals with round-ups
    • Freeze the card, ask for money
    Oaklet teen app: Luca's €86.40 balance, his fuchsia card, and €95.00 saved of €150.00 for headphones
  5. 05

    Rules parents set, alerts in seconds

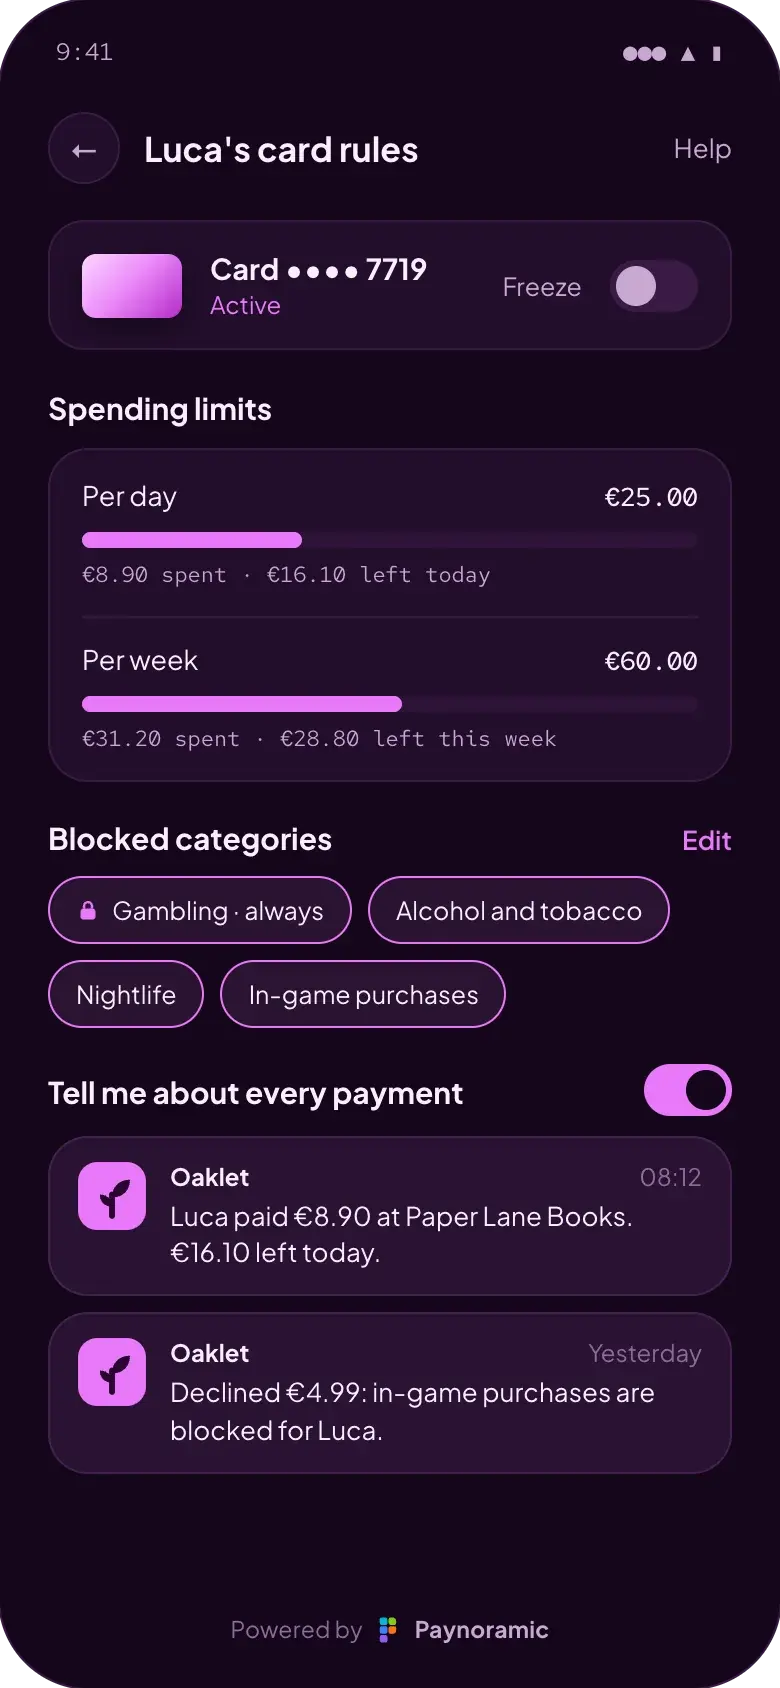
    Daily and weekly limits and blocked categories apply to every card payment as it happens. Parents get a notification for each payment, declined ones included.

    • Spending limits per day and per week
    • Blocked categories, such as gambling
    • A notification for every payment
    Oaklet card rules for Luca, powered by Paynoramic: a €25.00 daily limit, blocked categories and payment notifications
Oaklet family banking app onboarding, powered by Paynoramic: a parent adding Luca, 14, and Mia, 9, before giving consent
Oaklet parent view: the family account, and Luca's and Mia's balances, cards and latest payments
Luca's weekly allowance of €15.00 every Saturday, with chores worth up to €5.00 and one waiting for approval
Oaklet teen app: Luca's €86.40 balance, his fuchsia card, and €95.00 saved of €150.00 for headphones
Oaklet card rules for Luca, powered by Paynoramic: a €25.00 daily limit, blocked categories and payment notifications

Delivery

Two ways to launch your family banking app.

Ready platform

~30 days

Time to launch, on a 12-month scale

Assembled from modules already in production: accounts and IBANs, card issuing, payouts, portfolios, KYC and fraud controls. Parent and child accounts and the allowance, with its chores and savings goals, are built on those modules as part of the work; then we apply your brand, connect your partner bank and card issuer, deploy, and hand over the source code.

  • Your brand, your domain, your infrastructure
  • Full source code handed over at launch
  • No licence fee, no revenue share, no lock-in
Get this platform

Custom build

Recommended

2–3 months

Time to launch, on a 12-month scale

Gifts from grandparents and other relatives, more than one guardian per child, allowances in several currencies or school payments, assembled from the module library around the same proven core.

  • Assembled from the same proven modules
  • Scoped and priced per module, in writing
  • Same handover, same 100% ownership
Scope a custom build

Assembled from

Ten modules from the library.

Each one running in production before it reaches your platform. See the whole library

How it works

From brief to handover.

  1. 01

    Brief

    One call. Tell us the product, the market and the launch date. We map it to the modules that already exist.

  2. 02

    Configure

    We pick the modules, apply your brand and set up your infrastructure. Every piece is already proven in production.

  3. 03

    Deploy

    Your platform goes live on your domain, with your data, under your control.

  4. 04

    Handover

    Source code, documentation and the keys. The platform is yours, with no licence and no revenue share.

Questions

What buyers ask about a white-label family banking app.

Who holds the account, the parent or the child?

In most programmes, the parent: they pass the identity checks and hold the family account, each child gets an account and a card under it, and the app records the parent's consent for every child. Some partners also open accounts in a teen's own name with a parent's consent. Which model you can offer, and from what age a child can have a card, depend on your licence or your partner's and on local law.

Which banks and card issuers does it run on?

The accounts come from a licensed partner bank or e-money institution: the accounts module connects to banking-as-a-service providers such as ClearBank, Banking Circle, Modulr, Solaris, Swan and Treezor. The cards run on issuer processors such as Marqeta, Thredd, Nium, Paymentology and Enfuce, on Visa or Mastercard. We help you choose partners that cover your markets and support accounts for minors.

How do parents control spending?

Per child, from their own app: daily and weekly limits, blocked categories such as gambling and alcohol, the countries where the card works, and a freeze button. Every card payment is checked against those rules as it happens, and the parent gets a notification for each one, declined payments included.

Can children invest as well as save?

Yes, if you offer it. Savings goals come with every child's account, and the portfolios module adds investing through a broker-as-a-service partner such as Alpaca, DriveWealth or Upvest, which executes and holds the assets under its licence. For a child, a parent opens the investment account and approves what is bought.

What about licensing and compliance?

Holding a family's money and issuing cards is regulated: in the EU it takes an e-money or banking licence, in the UAE (outside the financial free zones) a stored value facility licence from the Central Bank, and similar elsewhere; many companies launch under a licensed partner first. Accounts for minors add rules of their own, such as a parent's consent, who holds the account, the youngest age for a card and extra protection for children's data under the GDPR. The app ships with KYC/AML checks, sanctions screening, fraud controls and an audit trail, configured for your legal setup.

Do I really own 100% of the app?

Yes. On launch you receive the full source code of the parent and teen apps, the family accounts and the allowance, the integrations and the backoffice, with infrastructure configuration and documentation. There is no licensing fee, no revenue share and no lock-in.
More platforms

Built from the same library.

Start your project

Tell us the idea. We'll show you the platform.

One call is enough to map your product to the modules that already exist.

  • Response in under one business day
  • NDA on request
  • No obligation
What are you building?